Developers pushed code changes to GitHub 17.9 billion times over the past 12 months, a figure that exceeds 2024 and 2025 combined. The behind-the-scenes activity tells a similar story: commits across public and private repositories reached 34.3 billion, more than triple the level of two years ago, while merged pull requests more than tripled to 1.3 billion over the same period — an average of 3.5 million per day.
How the pace accelerated
The year did not grow evenly. Telemetry shows activity climbing steadily from January before surging around June, when several industry-wide changes landed at once: stronger underlying models, the harnesses and tools built around them, and the agents running on both. Agents moved from single-session tools to persistent ones that track progress across days and orchestrate other specialized agents. They also began making heavier use of the cloud, executing work remotely as well as on local machines.
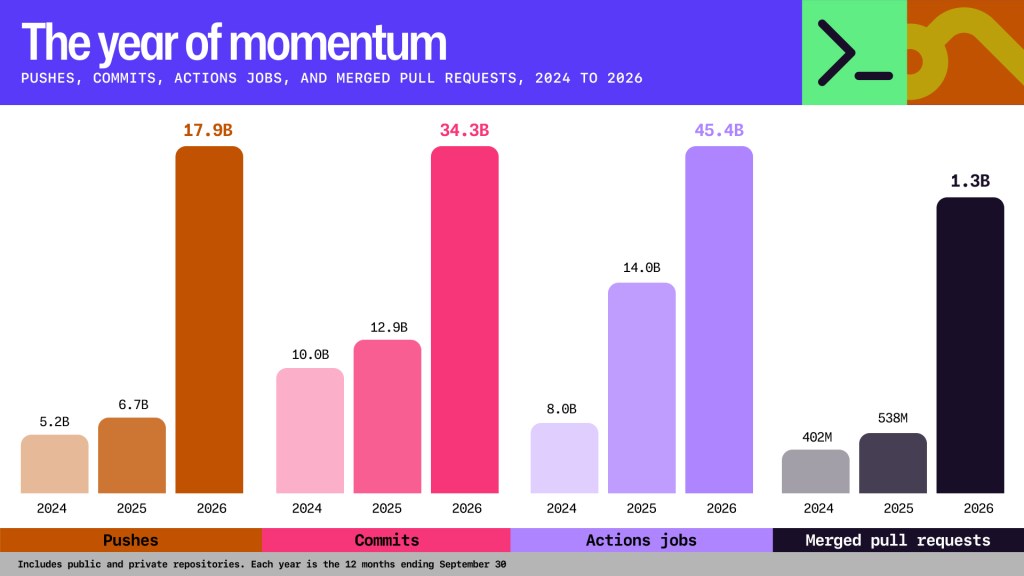
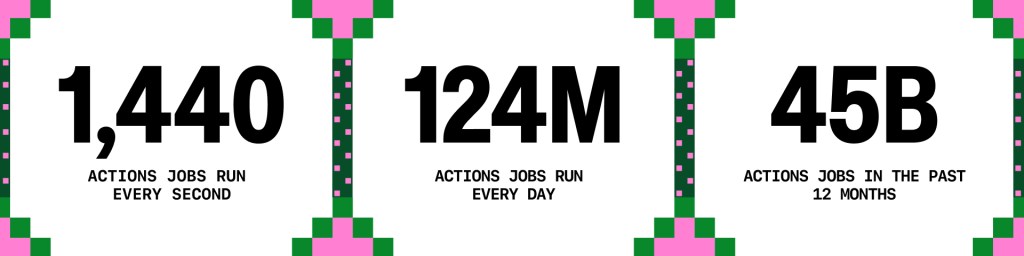
Among repositories created this year, those with an agent configuration file logged, on average, eight times as many commits as new repositories without one — a sign that individuals and teams building with agents from day one operate at a notably different pace. Automations filled in behind them: GitHub Actions ran a job 1,440 times every second, equivalent to 124 million jobs a day and more than three times last year's total. Developers also merged more than 30 million Dependabot pull requests to keep dependencies current and limit exposure to known vulnerabilities, roughly double 2025's rate.
Newcomers and long-standing contributors
Growth appeared in both fresh repositories and established work. From June onwards, roughly 55% of all commits came from brand new repositories, yet developers with a track record also stayed active. Those who pushed code in the past 12 months have been on GitHub for an average of 36 months, and of those who opened a pull request in August, more than 75% pushed code again in September. The average developer now works across 10% more repositories than a year earlier.
Open source reflects the same staying power: public contributions reached 2.5 billion in 2026, more than double last year's 1.12 billion. Some of that volume comes from individuals working at exceptional scale — @kinlane made over 1 million public contributions using agentic workflows to maintain a machine-readable catalog of public API information, @kim-em contributed more than 178,000 times while maintaining mathlib, the community library of computer-checked mathematics, and @andig, a maintainer of the EV charging controller and home energy management system evcc, contributed over 21,000 times.
Where the developer base stands
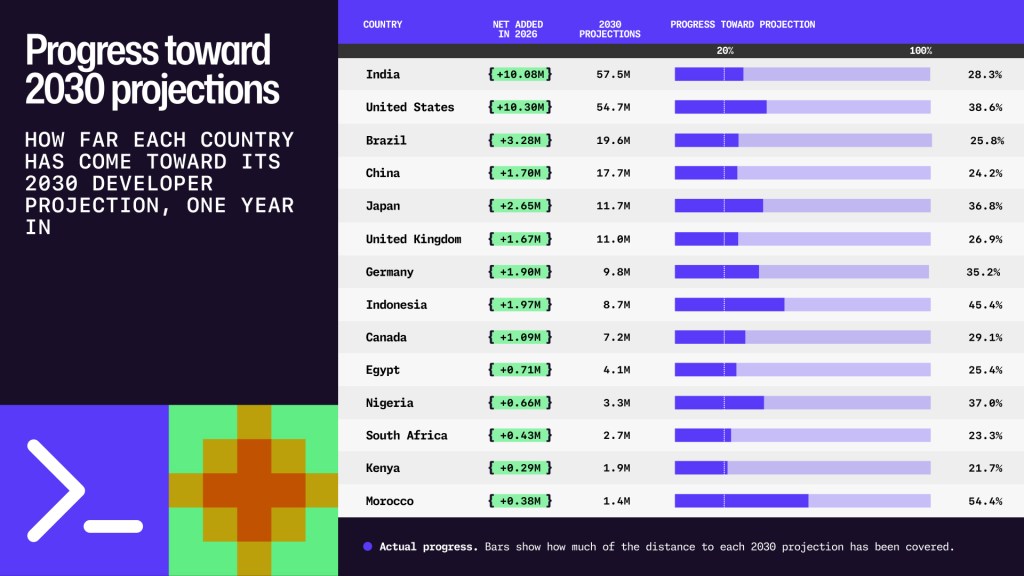
GitHub now serves more than 225 million developers. The United States (38.3 million) and India (32 million) remain the largest communities, each adding more than 10 million developers this year, while Brazil added 3.28 million — third most of any country.
| Country | Total number of developers on GitHub in Sept. 2026 |
|---|---|
| United States | 38.3 M |
| India | 32.0 M |
| China | 12.4 M |
| Brazil | 10.2 M |
| Japan | 7.15 M |
| United Kingdom | 6.47 M |
| Indonesia | 6.34 M |
| Germany | 6.30 M |
| Russia | 5.07 M |
| France | 4.75 M |
Last year's projection put India at 57.5 million developers by 2030 and the United States at 54.7 million. One year into that five-year window, every projected country has closed at least a fifth of the distance to its 2030 figure; the United States has closed 38.6% and India 28.3%.
| Region | Growth driver | Market context |
|---|---|---|
| Americas | Fintech and digital payments | • Brazil: mature, fast-growing fintech sector • Canada: steady AI and software investment |
| EMEA | AI adoption in manufacturing and startups. Fast-growing developer community in Africa | • Morocco: fintech and startup scene • Germany: enterprise AI adoption across its industrial heartland • France and Spain: AI and deep-tech startups • Kenya, Nigeria, South Africa: fintech, agritech, and coding bootcamps |
| APAC | Government investment in AI infrastructure and talent | • Indonesia: booming digital economy • Japan: AI infrastructure investment • South Korea: government-backed AI talent programs • Australia: AI, machine learning, and data skills |
Extending the forecast is now harder than before. Running more than 40 time-series and regression models forward to 2031, each built on historical sign-up and usage data and assuming a different pace of growth, produced a wide spread: about half of the models call for "extreme" growth, with developer counts more than tripling by 2031, just under half call for "substantial" growth of two to three times, and only three expect under 2x. The divergence itself measures how much the 2026 surge widened what is plausible — what holds steady is the shape of the trend, a community growing in more places at once.
Industry reach
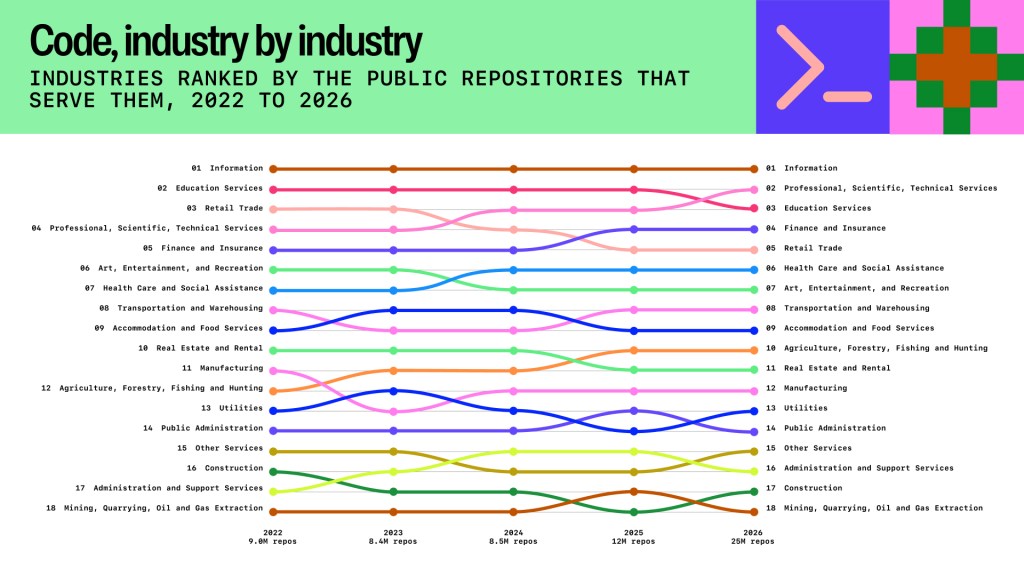
Where past reports treated "everywhere" as more developers in more countries, this year it also means more fields. Using the North American Industry Classification System (NAICS), a language model classified random samples of public repositories created each year from 2022 through 2026, assigning each to the industry it serves based on its name, description, topics, and README. Two further signals were tracked: whether a repository mentions AI, and whether an agent opened a pull request against it.
The signals diverge by sector. In administrative and support services, mining, health care, and agriculture, more than four in 10 repositories mention AI, yet agent-opened pull requests remain rare at less than 3 percent. Construction breaks the pattern: about a quarter of its repositories mention AI, but about 9 percent have agent-opened pull requests, the highest share of any sector, with manufacturing next.
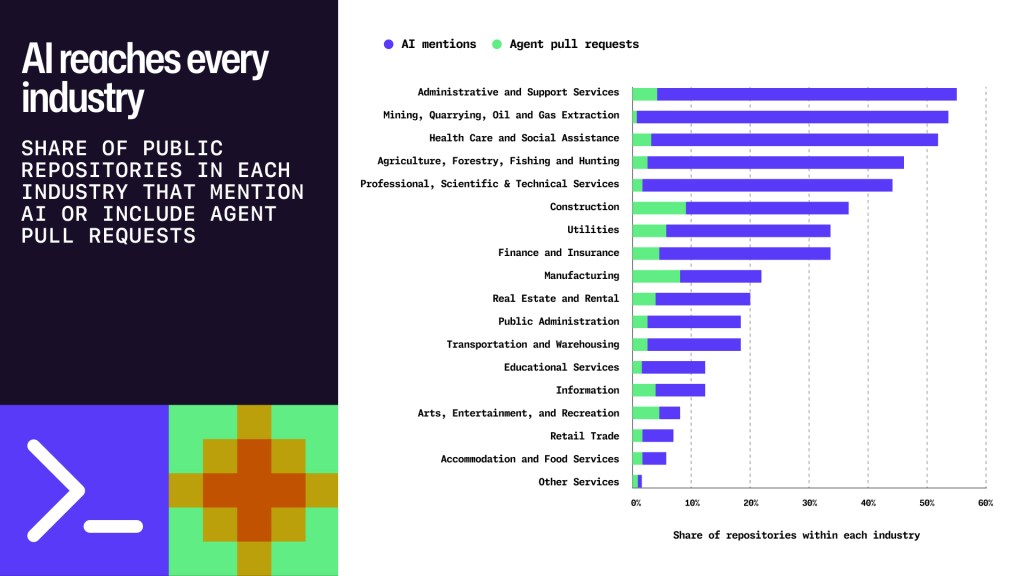
The classification also shows how each industry's footprint has shifted since 2022. Professional, scientific, and technical services climbed from fourth to second place among all industries, behind only information. Agriculture, forestry, fishing and hunting rose two spots, and finance and insurance and health care and social assistance each moved up one. Measured against each sector's own 2022 baseline, mining, quarrying, and oil and gas extraction grew roughly 65 times from a small starting base, administrative and support services and construction 17 to 18 times, and manufacturing, the slowest of these, almost tripled.
How agent-driven work changed the developer workflow
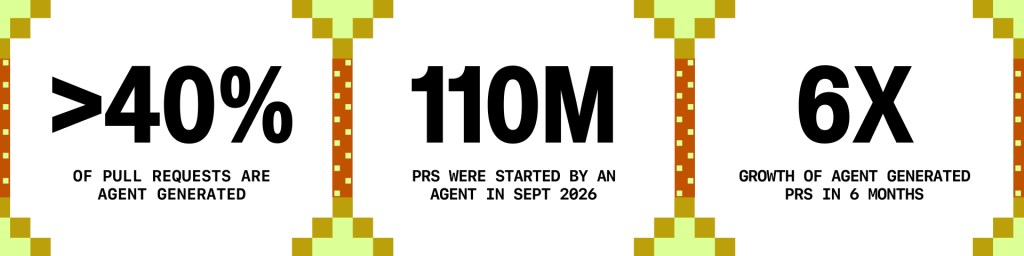
Pull requests increasingly open with an agent's first draft rather than a human's. By September 2026, more than 40% of pull requests on GitHub were started that way, nearly 2.5x the 17% seen in March. Volume reached 110 million in September alone, roughly six times March's figure.
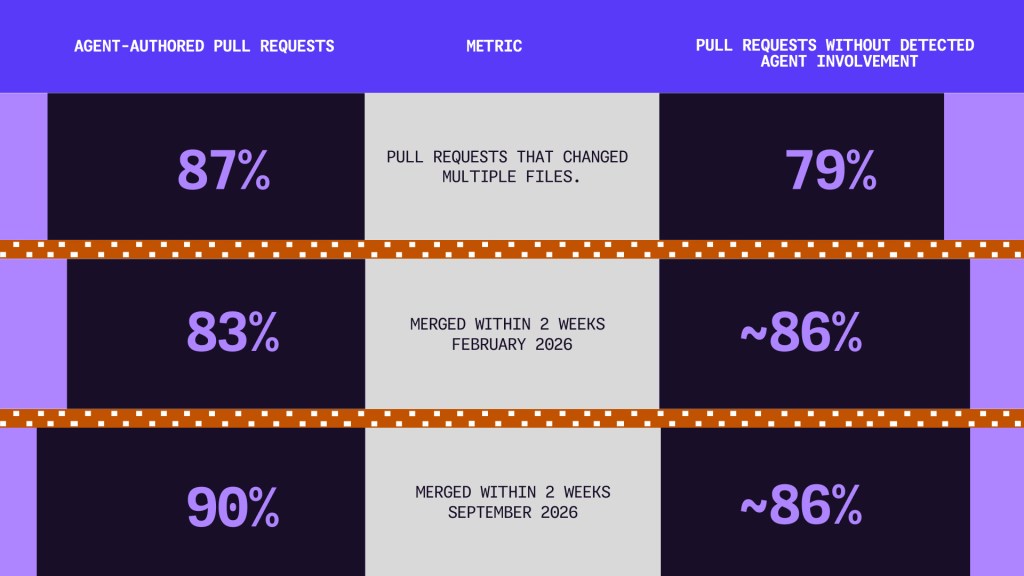
Work from agents also tends to span more of a codebase: about 87% of these pull requests touch multiple files, versus 79% of those without detected agent involvement. They merge quickly as well. In February, 83% of agent-involved pull requests merged within two weeks, slightly behind the roughly 86% for pull requests without detected agent involvement. By September the agent group had reached 90%, while the comparison group held at about 86%.
Inside GitHub Copilot, 55% of monthly active users now use agentic features, up from 35% a year earlier. The sharpest growth is in the most hands-off option: Copilot cloud agent, where a developer assigns a task and an agent works on it independently, grew 230% year over year, compared with 85% for agent chat. Asking questions is still common, but developers are increasingly handing over entire tasks.
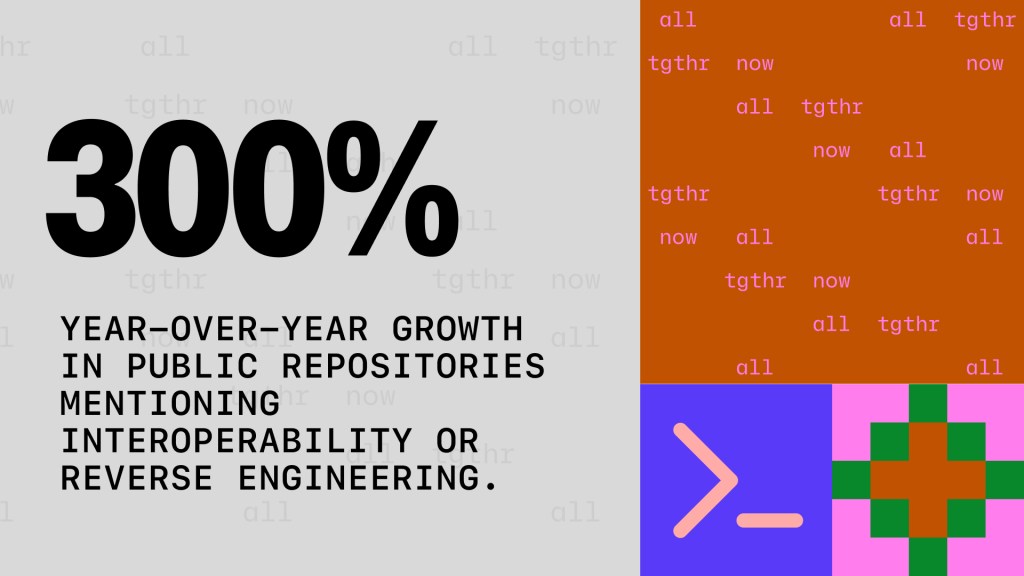
The scope of what they delegate shows up in repository activity: public repositories mentioning interoperability or reverse engineering rose more than 300% year over year, from about 30,000 created in 2025 to more than 130,000 in 2026.
Review is where developers exercise control over what comes back, and tooling for it is expanding. Stacked pull requests, which break related work into a sequence of smaller changes reviewed in order, shipped as a preview on July 30, and more than 264,000 developers had used them by September. AI-assisted code review and GitHub Advanced Security each grew more than 90% year over year. Push protection, which screens for exposed secrets such as API keys and passwords, ran 5.8 billion scans this year, nearly four times 2025's pace.
Developers spread their model choices
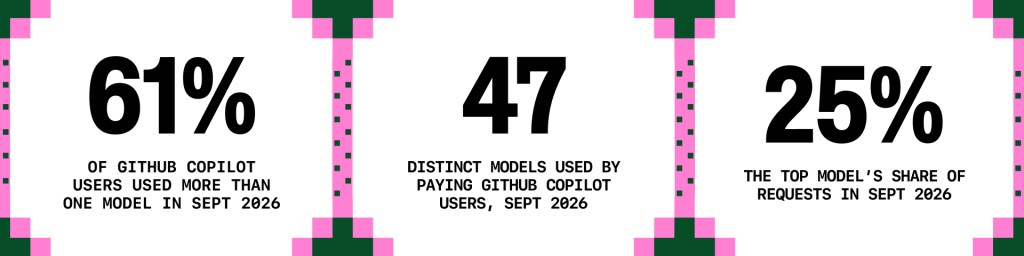
Model selection moves at the pace of the work. In September 2026, 61% of GitHub Copilot users who picked a model themselves used more than one across their sessions, up from 50% four months earlier.
The roster keeps expanding: developers on paid Copilot plans used 29 distinct models in May and 47 in September, and no single model carried more than 25% of requests that month. Cost and familiarity factor in, with developers weighing price and functionality against their needs and leaning toward providers they already trust.
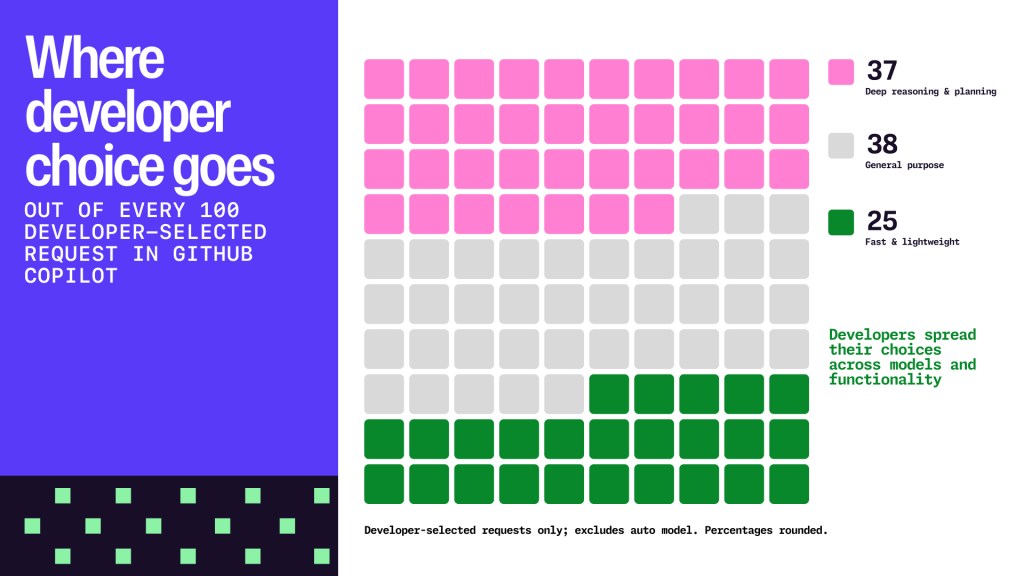
To measure how usage spreads, the analysis grouped models by purpose — deep reasoning and planning, general purpose, and fast and lightweight — and counted only requests where a developer explicitly selected a model. Excluded: auto model selection, GitHub and Microsoft staff usage, background utility models, duplicate requests used for monitoring and testing, and requests made with a developer's own API key.
Per 100 developer-selected requests, 38 went to general purpose models, 37 to deep reasoning and planning, and 25 to fast and lightweight models.
Three patterns emerged from tracking request share, model trial and return usage over three months:
- New releases get heavy use early. In their first weeks, most new models take a larger share of requests than the share of developers who have tried them.
- Developers don't drop models abruptly. When a model's share of requests declines, the share of developers still using it falls more slowly.
- Developers mix categories. Requests spread across all three groups, and few developers stay with any one kind for long.
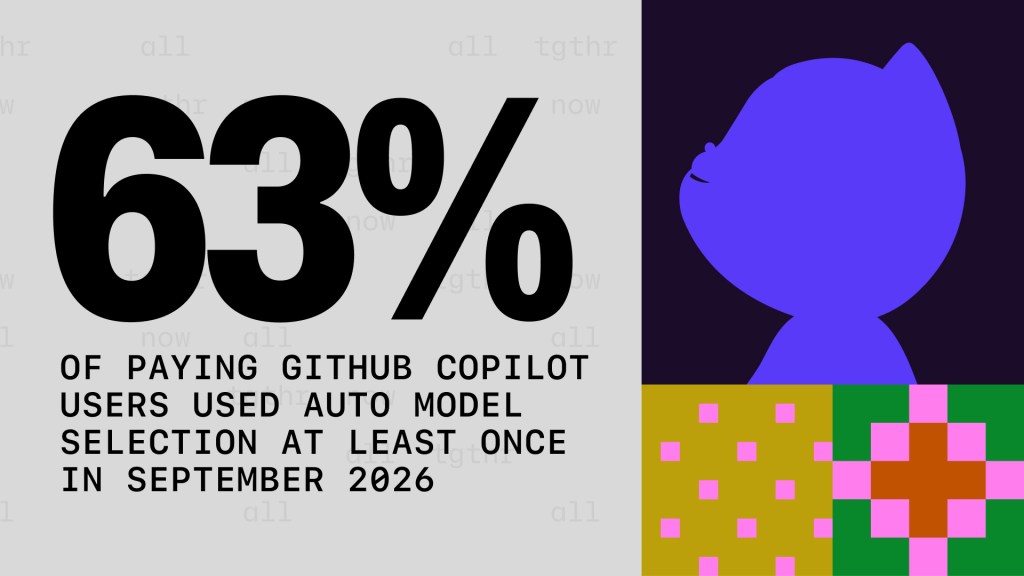
Many developers also delegate the decision: 63% of paying Copilot developers used auto model selection at least once in September 2026. That fits the shape of the work — planning, implementing and checking a change each place different demands on capability, speed and cost. Project HydraFusion, a research preview of model orchestration, routed almost 60,000 sessions in the CLI and the Copilot app. It is now generally available as GitHub Copilot Fusion, combining orchestration with auto model selection to choose the right model for each step behind the scenes.
A fourth influence on language choice
Language choice has traditionally reflected what developers want to build, what their teams know, and what existing systems require. This year's data raises the question of a fourth: the language an agent picks when none is specified.
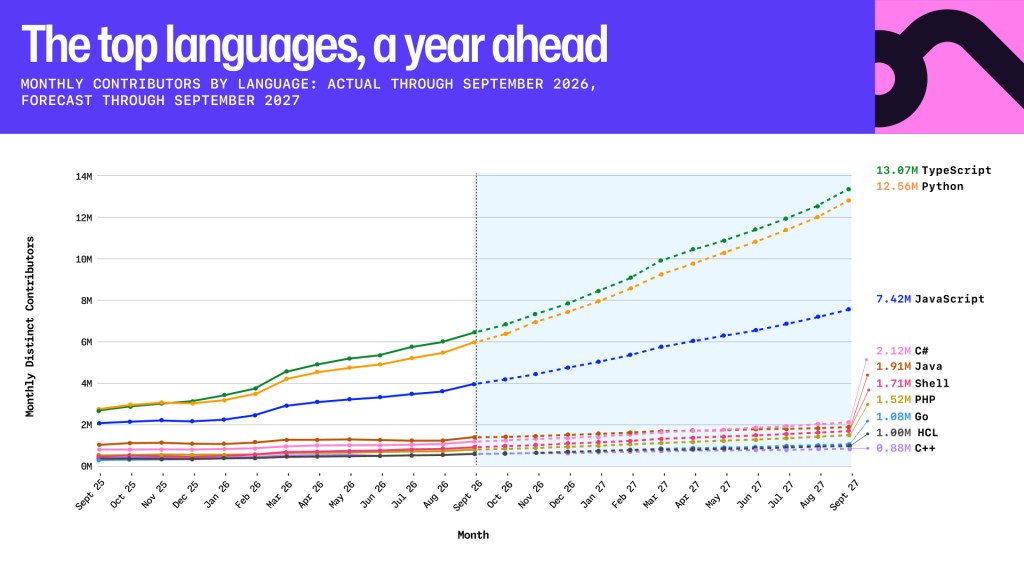
TypeScript led in 2026, followed by Python and JavaScript, preserving last year's order. Gains accelerated: from September 2025 to September 2026, TypeScript added 3.62 million monthly contributors, Python 3.23 million and JavaScript 1.82 million — the largest among the top 10. Rust grew fastest by percentage among top languages, doubling in the past year. Forecasts point to TypeScript and Python at near 13 million monthly contributors each by September 2027, JavaScript at 7.4 million, and every other top-10 language below about 2.2 million.
The fastest-growing languages are also where AI is most visible. Plotted against the share of merged pull requests with detected AI involvement, TypeScript, Python and Rust show the highest shares, about 40% to 44%. Java, C#, and C++ sit lower, between about 21% and 34%, though AI appears in more than one in five merged pull requests in every language shown.
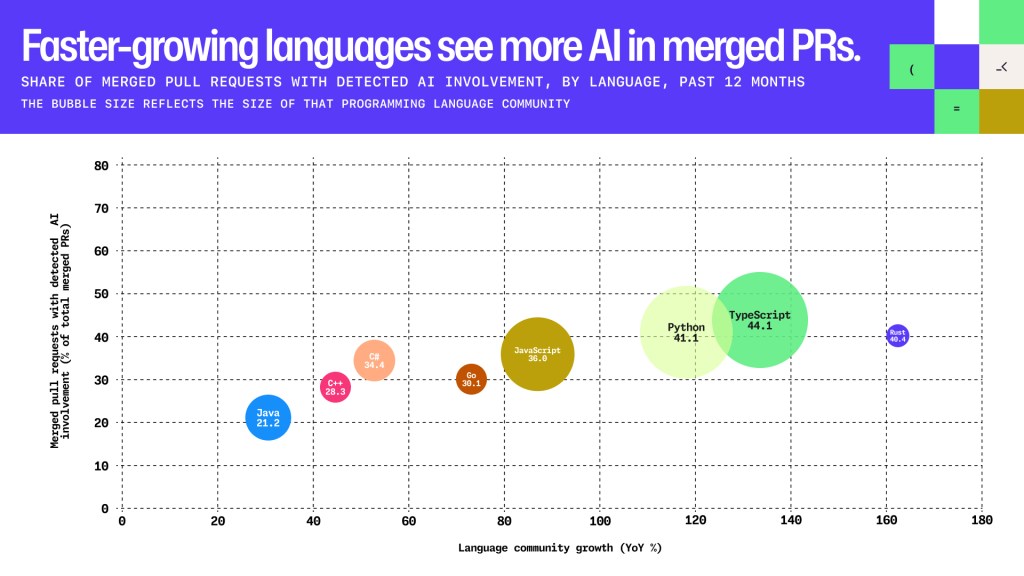
Repository data points the same way. Among repositories created in 2026, TypeScript was the primary language in 35% of those with an observed agent signal versus 24% without one; for older repositories the gap was comparable, 27% versus 17%. Developers still specify a language when they know what they want, but when the choice is left open, agents appear to favor a narrower set, with TypeScript first among them.
Where attention and contributions go
The fastest-growing and most-engaged projects were split into community and independent repositories — foundation-governed, broadly maintained, or led by an individual without a clear commercial sponsor — and single-vendor or product-led ones, where strategic control sits with one company even when community contributions are substantial.
Taken together, the lists show a division of labor. The community side supplies the foundation: inference engines such as vLLM, SGLang and llama.cpp; frameworks such as PyTorch; languages and runtimes such as Rust and CPython; platforms such as Home Assistant and Godot. The vendor side supplies the tools developers touch directly: coding agents, editors and the orchestration around them. Growth lists also include places built for newcomers, such as first-contributions and is-a-dev/register, where many developers open their first pull request.
| Rank | Community / independent | Single vendor / product-led |
|---|---|---|
| 1 | farion1231/cc-switch | Anthropic: anthropics/claude-code |
| 2 | punkpeye/awesome-mcp-servers | OpenAI: openai/codex |
| 3 | Omacom Foundation: omacom/omarchy | Anomaly: anomalyco/opencode |
| 4 | firstcontributions/first-contributions | Microsoft: microsoft/vscode |
| 5 | ggml-org/llama.cpp | GitHub: github/copilot-cli |
| 6 | Eclipse Foundation: EclipseFdn/open-vsx.org | Zed Industries: zed-industries/zed |
| 7 | sgl-project/sglang | Google: google-gemini/gemini-cli |
| 8 | vllm-project/vllm | BerriAI: BerriAI/litellm |
| 9 | imputnet/helium | microsoft/winget-pkgs |
| 10 | vllm-project/vllm-ascend | Kilo-Org/kilocode |
| Rank | Community / independent | Single vendor / product-led |
|---|---|---|
| 1 | OpenClaw Foundation: openclaw/openclaw | Nous Research: NousResearch/hermes-agent |
| 2 | vllm-project/vllm | Anomaly: anomalyco/opencode |
| 3 | ggml-org/llama.cpp | Earendil: earendil-works/pi |
| 4 | Omacom Foundation: omacom/omarchy | Stably AI: stablyai/orca |
| 5 | farion1231/cc-switch | Ping: pingdotgg/t3code |
| 6 | sgl-project/sglang | Microsoft: microsoft/vscode |
| 7 | PyTorch Foundation: pytorch/pytorch | Graphify Labs: Graphify-Labs/graphify |
| 8 | Rust Foundation: rust-lang/rust | Paperclip AI: paperclipai/paperclip |
| 9 | Open Home Foundation: home-assistant/core | BerriAI: BerriAI/litellm |
| 10 | Python Software Foundation: python/cpython | can1357/oh-my-pi |
The decisions that remain with developers
The rocket 🚀 was the most-used emoji across every industry surveyed, by a wide margin. Developers covered more ground this year — more code, more countries, more industries than previously measured — but nothing about that changes who decides what the code should do. Someone still has to have the idea, whether it assesses earthquake risk, records how online services change their terms and privacy policies, or makes an AI answer like a caveman to save words. And someone still has to judge whether it works, belongs, and is good.
What has changed is the distance between a weekend thought and something real. Tools will keep shifting and new industries will keep appearing in unexpected places; what to build, and for whom, remains the developer's call.
Definitions
- Agent configuration file: A repository file that sets up or directs an AI coding agent, also called an AI configuration file or agentic file. Repositories without one may still use AI.
- Agent signal: An observed sign of agent involvement in telemetry, such as an agent-opened pull request; a floor, since not all agent use may be detected.
- Agent-started pull request: A pull request whose first draft came from a detectable coding agent.
- Auto model selection: A GitHub Copilot setting where Copilot picks the model for the task.
- Commit: A saved snapshot of changes to a repository.
- Contributions: Activity events — commenting on a commit, issue, pull request or discussion; creating a gist, issue, pull request or discussion; pushing code; reviewing a pull request. Each push counts once regardless of commits. Open-source contributions go to public and open source repositories.
- Contributors: GitHub users with at least one contribution in the period.
- Copilot cloud agent: A Copilot feature where a developer assigns a task and an agent works on it independently.
- Dependabot: GitHub's automated tool that finds outdated or vulnerable dependencies and opens pull requests to update them.
- Developer-selected request: A model request where the developer chose the model; excludes auto model selection, staff usage, duplicate monitoring and testing requests, background utility models, and requests made with a developer's own API key.
- GitHub Actions job: A single unit of work in a GitHub Actions workflow.
- GitHub Advanced Security: GitHub's suite of application security features, including code scanning, secret scanning and dependency review.
- NAICS: The North American Industry Classification System, used this year to classify public repositories by industry.
- Project HydraFusion: A GitHub research preview of model orchestration — planning a task across models, such as one drafting, another reviewing, and a more capable one stepping in when needed. Now generally available as GitHub Copilot Fusion.
- Push: Sending saved changes to GitHub; one push can carry many commits.
- Stacked pull requests: A review workflow that splits related work into a sequence of smaller pull requests reviewed in order.
How the numbers were produced
The reporting year spans October 1, 2025 through September 30, 2026, and covers public and private repositories together unless a metric is called out as public-only. That exception applies to industry figures, open-source contribution totals, and open-source project data. For 2024 and 2025, the figures were recomputed under the current definitions and the current window, so they can diverge from numbers in earlier editions, which tracked public activity over a September 1 to August 31 period.
Counts and exclusions
A push carries one or more commits, and each push is counted once as a contribution. Commit totals can therefore run above contribution totals. Actions usage is reported in jobs rather than minutes, and the 2.5 billion open-source contributions are public-scope figures. Spam-flagged accounts, staff, and bots are removed from contributor and contribution tallies wherever they can be identified.
Geography
Country assignment relies on self-reported location, and a country appears only once it reaches 100 developers. The 2025 report published totals for 2030 instead of yearly targets; progress toward those numbers is measured as net developers added between September 2025 and September 2026, expressed as a share of the remaining distance from each country’s 2025 count to its 2030 projection. For push rankings, pushes to public repositories were summed across the year and adjusted by profile location: an LLM classifier extracted ISO 3166-1 alpha-2 codes from contributor profiles, ratios were built comparing profile-derived codes with IP-derived codes, and those ratios weighted each country’s push volume to offset VPN bias.
Language and model data
A language contributor is a distinct account counted once per month if it pushed, opened or reviewed a pull request, filed an issue, or commented, with activity attributed via Linguist to each repository’s primary language; the same account can appear under several languages. Forecasts, following the 2025 method, cover the top 10 languages by average monthly participation and extend to September 2027 with the mean shown. The bubble chart plots growth in monthly participating accounts from September 2025 to September 2026 against the share of merged pull requests showing detected AI involvement, sized by community.
Copilot model figures count developer-selected requests only, excluding auto model selection, staff activity, duplicate monitoring requests, background utility models, and requests made with a developer’s own API key. A model must reach at least 1,000 weekly active users to be included. Models are grouped by intended use, with examples listed alphabetically by provider:
- Deep reasoning and planning: Claude Opus 5.5, GPT 5.5.
- General purpose: Claude Sonnet 5, Grok 4.7, GPT 6.1 Sol.
- Fast and lightweight: Claude Haiku 5.5, Gemini 3.8 Flash, GPT 6 Luna.
These figures describe observed usage rather than model quality. Trends draw on weekly data from July 14 to October 13, 2026, and request share is each model group’s portion of qualifying requests in the 7-day period ending October 13, 2026.
Industry, rankings, and forecasts
For industry classification, public repositories created between 2022 and 2026 were assigned NAICS sectors by a fine-tuned multilingual embedding model reading name, description, topics, and README from random samples per year. AI mentions and agent-opened pull requests (detectable agents only) were flagged as separate signals; because sector assignment and AI detection read the same text, the two shares can be related, and all shares are estimates. Open-source lists divide repositories into community and single-vendor classes by who holds strategic control. “Fastest-growing” ranks by the absolute year-over-year increase in distinct contributing accounts, “most engaged” blends rankings for stars, forks, and distinct pull request and issue creators, and forks are excluded from both.
Interoperability counts public repositories created each year whose name, description, topics, or README reference interoperability, reverse engineering, or related terms such as clean room implementation, drop-in replacement, or protocol re-implementation. Developer forecasts applied 43 time-series and regression models to historical GitHub data, sign-ups, product usage, and market sizing, projecting to September 2031 against September 2026: 21 models land at 3x or more, 19 between 2x and under 3x, and 3 below 2x. The 2025 edition used five models. No forecast is perfectly accurate.